1. Global Brands Are Quietly Rewriting the Economics of Advertising Agencies
The agency business is moving from selling hours to selling outcomes, and artificial intelligence is accelerating the transition.
One of the more consequential changes taking place in global marketing is happening far from the glamour of Cannes or the launch of the latest global campaign. It is happening inside procurement departments. Research by the World Federation of Advertisers and Agency Mania Solutions shows that labour-based remuneration – the traditional model in which brands largely pay agencies for people, time and resources – has fallen sharply among multinational advertisers. Only 19% of respondents now use labour-based models as their standard approach, down from 54% in 2011. Fixed-fee or output-based arrangements have risen to 33%, while labour-plus-performance models have reached 21%.
The direction of travel is even clearer. Among the 69 multinational companies surveyed, representing $147 billion in collective global marketing expenditure, 63% expect performance-based remuneration to increase, while 46% anticipate greater use of value-based models. Artificial intelligence is helping to push the industry towards this reckoning because agencies can increasingly produce more assets, versions and executions in less time. Only 20% of brands have already changed their commercial models because of AI, but 61% intend to do so.
For agencies, this is potentially more disruptive than AI-generated copy or images. If clients become less willing to pay for labour and increasingly interested in measurable outputs, agencies will have to demonstrate why their strategic thinking, creativity, relationships and intellectual capital deserve to command value even when production becomes cheaper. For Nigerian agencies, the lesson is uncomfortable but useful: the future agency pitch may increasingly be about the business value of an idea rather than the number of people required to produce it.
The WFA research also reveals a paradox. Although 89% of brands believe they receive value for money from agencies, only 48% say they have sufficient transparency into agency costing and profitability. The next phase of the client-agency relationship may therefore depend less on cheaper fees than on greater transparency about where value is created.
BrandiQ Takeaway: AI may not destroy the advertising agency. It may destroy the logic by which some agencies have traditionally priced themselves. The agencies most likely to remain valuable will be those capable of connecting creativity to commercial outcomes while demonstrating the strategic value that machines cannot easily commoditise.
2. Nigeria’s Smartphone Boom Is Turning the Country into a More Intensely Mobile Economy
Smartphone ownership has reached 75%, creating a larger digital market – but also exposing the limits of assuming that digital access equals digital inclusion.
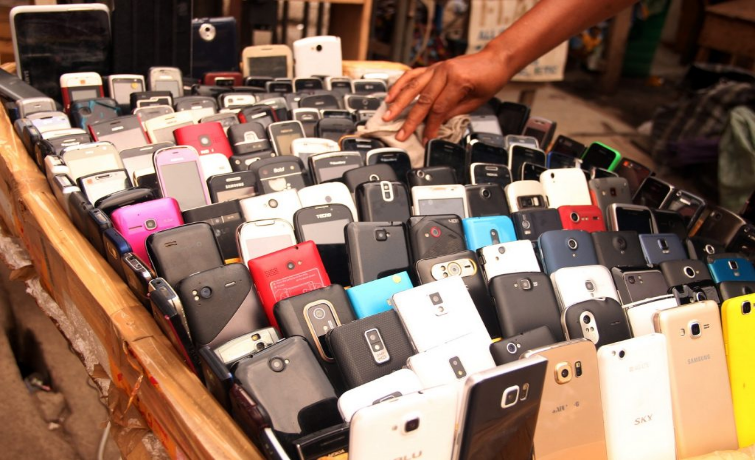
Nigeria’s smartphone economy has crossed an important threshold. A new KPMG Nigeria study, based on research involving 13,251 respondents across 12 major Nigerian cities, says smartphone penetration rose from 64% in 2023 to 75% in 2025. The research describes smartphones as increasingly important not merely for communication but for financial services, commerce, entertainment, education, transportation and wider economic participation.
The numbers are significant for brands. The Nigerian consumer is becoming increasingly reachable through a device that accompanies him or her throughout the day. That changes how companies think about customer acquisition, payments, customer service, entertainment, advertising and even product design. A bank no longer needs to think about a banking customer primarily as someone who enters a branch; a retailer can design around mobile discovery and payment; a media company can build around a permanently connected audience; and a consumer brand can increasingly move from periodic advertising to continuous engagement.
But the headline number conceals an important qualification. KPMG notes that more than a third of mobile subscribers were still using 2G as of May 2026, while affordability, infrastructure limitations, digital literacy and cybersecurity remain constraints. The NCC’s May figures cited in the report put internet subscriptions at 157 million, with data consumption exceeding 1.5 million terabytes. The Information and Communication sector accounted for 11.31% of real GDP in the first quarter of 2026.
For marketers, this means that “digital Nigeria” is not one market. A smartphone-owning consumer with fast, affordable data is a very different commercial proposition from someone technically connected but constrained by device quality, data costs or network performance. The next frontier for Nigerian brands is therefore not simply digital adoption but digital depth – how frequently, reliably and meaningfully consumers can use digital services.
BrandiQ Takeaway: Seventy-five percent smartphone penetration makes mobile central to Nigerian brand strategy. But the sophisticated marketer will resist treating connectivity as a binary condition. The real opportunity lies in designing experiences that work across differences in device quality, bandwidth, income, literacy and trust.
3. AI Is Making Workers More Productive. Why Isn’t It Making Companies Richer?
McKinsey’s latest global survey exposes a widening gap between what employees gain from artificial intelligence and what companies are capturing from it financially. The next AI race may therefore be less about adoption than about redesigning the business around the technology.
There is a paradox emerging at the centre of the corporate artificial-intelligence boom. Employees are increasingly discovering that AI can make them faster, more productive and, in some cases, better at their jobs. Companies, meanwhile, are spending heavily to deploy the technology across departments, automate processes and experiment with increasingly capable AI agents. Yet the financial payoff at enterprise level remains much less widespread.
McKinsey’s latest State of AI in 2026 survey puts the gap into unusually stark numbers. Eight in ten respondents say AI has improved their individual productivity, but only 37% report that AI has contributed positively to their organisation’s EBIT. The proportion of respondents qualifying their organisations as AI “high performers” – those attributing at least 5% of EBIT to AI and describing its impact as significant – is only about 6%.
The finding matters because the first phase of the corporate AI revolution was largely about adoption. Companies wanted employees to experiment with generative AI, introduced copilots, built proofs of concept and began deploying AI agents. The next phase is more demanding. Boards and chief executives will increasingly want to know what all this technology is actually doing to revenue, costs, margins, customer experience and competitive advantage.
The question is no longer whether employees can use AI. It is whether the organisation itself has changed because of AI.
The Productivity Trap
The easiest AI gains are often the most visible ones. An employee can use an AI assistant to summarise a report, draft an email, analyse information, write code or prepare a presentation in considerably less time. Multiply those improvements across thousands of employees and the productivity gains can appear substantial. But individual productivity does not automatically become corporate productivity.
An employee may complete a task faster only to discover that the next stage of the process remains dependent on another department. A salesperson may generate more proposals, but if the approval process is unchanged, revenue may not rise. A marketing team may produce ten times as much content, but if the company’s customer insight, distribution or measurement systems remain unchanged, the additional output may simply create more noise.
This is what makes McKinsey’s 80%-versus-37% finding so important. It suggests that the technology is already producing meaningful benefits at the level of individual work, while organisations are struggling to translate those gains into broad financial performance. The problem may therefore be less about the capability of AI than about the architecture of the companies deploying it.
AI Cannot Transform a Workflow It Has Been Added To
McKinsey’s research points towards an important distinction between companies that are experimenting with AI and those beginning to extract substantial value from it. The high performers are more likely to redesign workflows around AI rather than simply insert AI into existing processes. They are also more likely to pursue growth and innovation alongside efficiency. This sounds technical, but it is fundamentally a management issue.
Consider a customer-service operation. Giving employees an AI assistant that drafts responses may make individual agents faster. But a deeper transformation would reconsider the entire customer journey: which enquiries should be automated, which require human judgment, how customer data should flow between systems, when an issue should escalate and how the organisation learns from recurring complaints.
The first approach adds a tool. The second redesigns the business. That distinction is likely to become one of the defining management questions of the AI era.
The Cost of Experimentation Is Rising
There is another reason the ROI question is becoming more urgent: AI is not free simply because software makes work faster. McKinsey reports that about 20% of respondents say AI-related operating costs are constraining their organisations’ use of the technology, even though most expect AI investment to increase. The economics become particularly important as organisations move from small experiments to enterprise-scale deployment, where computing, data, integration, security and governance costs become more consequential.
Infosys’ latest research reaches a complementary conclusion. Its survey of more than 1,000 senior executives at large US companies found that two-thirds of executives say their organisations struggle to measure AI ROI, while nearly three-quarters report that fewer than 25% of AI pilots have both scaled to enterprise deployment and delivered their intended ROI.
That does not mean AI is failing. It means companies are discovering that the difficult part of AI is moving from demonstration to scale.
The Measurement Problem
There is also a problem with the way businesses think about return. Executives naturally look for revenue. But Infosys’ research suggests that some of the strongest measurable benefits of AI are currently appearing in speed to market, operational efficiency and cost reduction, rather than immediate revenue growth. Two-thirds of the executives surveyed said their organisations struggle to measure AI ROI, and nearly half lacked a centralised framework for tracking its value.
This creates a peculiar situation. A company may be receiving genuine benefits from AI without being able to quantify them properly. If a product-development cycle becomes 20% faster, for example, the financial benefit may not appear as a line item called “AI revenue”. If a customer-service team resolves complaints faster, the value may emerge through retention, lower operating costs and improved customer satisfaction. If an analyst spends hours rather than days preparing intelligence for management, the gain may appear as faster decision-making rather than immediate revenue.
The lesson is not that companies should lower their standards for AI investment. It is that they need better definitions of value.
The New Competitive Divide
This could create a new divide between companies that merely use AI and those that reorganise around it. The distinction is already visible in McKinsey’s research. Only about 6% of respondents fall into its category of AI high performers. These organisations are more likely to pursue growth and innovation alongside efficiency, use a wider range of AI capabilities, redesign workflows and establish the leadership and operating disciplines required to scale the technology.
That is a significant warning for executives. AI may eventually become ubiquitous enough that simply having access to powerful models provides little competitive advantage. The advantage will instead come from what a company has built around those models: proprietary data, redesigned processes, employee capability, customer relationships, governance systems and organisational speed. The technology may become increasingly available. The organisational capability to exploit it will not.
What This Means for Marketers
The implications extend directly into marketing and communications. Generative AI can dramatically reduce the cost of producing content. It can create multiple versions of advertisements, analyse customer feedback, assist with research, personalise communications and accelerate campaign development. But if every competitor gains access to essentially the same tools, production efficiency alone will not create lasting differentiation.
The strategic advantage will shift towards the quality of the insight behind the machine. A brand that uses AI to generate 500 pieces of content is not necessarily more sophisticated than one that produces 50. The question is whether the technology has enabled the company to understand its customers better, make better decisions, improve experiences or allocate marketing investment more effectively.
AI can make a weak strategy faster. It can also make a strong strategy much more powerful. Knowing the difference will become a management discipline.
BrandiQ Analysis: The AI Question Has Changed
The corporate AI debate is moving through an important transition. The first question was: Can AI do this? The second became: How quickly can we deploy it? The third – and potentially the most consequential – is becoming: What should we redesign because AI can now do it? That is a much harder question.
It requires chief executives to look beyond technology procurement and examine workflows, organisational structures, incentives, skills, data architecture and decision-making. It requires finance directors to develop credible ways of measuring benefits that do not appear immediately on the income statement. It requires marketing leaders to distinguish productivity from effectiveness. And it requires boards to ask whether AI investment is changing the economics of the company or merely increasing the number of tools employees have at their disposal.
The companies that answer those questions well may discover that the greatest value of AI does not come from asking machines to perform existing work faster. It comes from questioning why the work is organised that way in the first place.
BrandiQ Takeaway
The most revealing AI statistic may not be the number of companies adopting the technology. It may be the distance between 80% of employees reporting greater productivity and only 37% reporting positive enterprise EBIT impact.
That gap is where the next phase of the AI economy will be fought. For business leaders, the lesson is increasingly clear: AI adoption is becoming a commodity; AI-enabled organisational transformation is not. The companies that capture the greatest value may not be those that buy the most AI tools. They may be those willing to redesign the business so that the tools change how the organisation actually works.
4. Anthropic’s Extraordinary AI Bet Raises a Bigger Question About the Economics of Artificial Intelligence
Anthropic’s prospective public listing is putting an uncomfortable fact about the AI boom under the spotlight: extraordinary growth can coexist with extraordinary capital requirements.
Anthropic’s IPO prospectus, reported by Reuters, provides an unusually revealing glimpse into the economics of frontier AI. The company generated nearly $4.6 billion in revenue in 2025 after revenue increased roughly twelve-fold, but it also reported a net loss of about $42 billion and expects enormous future commitments for computing and infrastructure. Reuters reported that the company has obligations involving roughly $518 billion in cloud, computing and infrastructure spending in coming years.
The figures matter because they challenge the easy assumption that rapidly growing AI companies automatically possess attractive economics. Building frontier models requires enormous computing power, data-centre capacity, energy and specialised chips. AI may ultimately transform productivity across the global economy, but the companies building the underlying infrastructure must spend heavily before that productivity becomes broadly monetised.
There is also a concentration risk. Reuters’ examination of the prospectus highlights Anthropic’s dependence on a small group of customers and technology giants. The AI economy therefore contains an intriguing contradiction: companies are trying to build businesses that could decentralise intelligence across the economy while simultaneously depending on a relatively concentrated infrastructure and capital ecosystem.
For African businesses, the significance is not whether Anthropic’s eventual valuation proves justified. It is what the economics imply about access to AI. If frontier AI remains extraordinarily capital-intensive, the competitive advantage may accrue increasingly to companies that control computing infrastructure, distribution, data and enterprise relationships. African businesses may consequently need to think less about building frontier models from scratch and more about intelligently applying existing AI infrastructure to local problems.
BrandiQ Takeaway: The AI race is not merely a race to build better models. It is a race involving chips, cloud infrastructure, energy, capital, data and distribution. The companies that understand this wider economic architecture will be better placed to distinguish an AI opportunity from an expensive technological fashion.
5. Nigeria’s Economy Is Growing Faster, but the Recovery Has Not Yet Become a Broad Business Boom.
Nigeria’s second-quarter growth accelerated to 4.43%, but the headline masks a more complicated economic reality for companies and consumers.
Nigeria’s real GDP expanded by 4.43% year-on-year in the second quarter of 2026, according to the National Bureau of Statistics figures reported in September. That was stronger than the 3.89% recorded in the first quarter and 4.23% in the corresponding quarter of 2025. Services remained the largest contributor to economic activity, accounting for 56.62% of real GDP.
The improvement is significant because it suggests that the reforms and macroeconomic adjustments of recent years are beginning to produce stronger aggregate growth. The World Bank says Nigeria’s real GDP grew 4.2% in the first half of 2026, with services and agriculture among the principal drivers, while reserves reached $51.9 billion at the end of July.
Yet growth remains only part of the story. The World Bank notes that inflation, food prices and weak real income growth continue to constrain households, while the economy’s growth rate remains insufficient to generate enough productive jobs and materially reduce poverty. It also reports that food inflation reached 20.3% in July.
For brands, this creates a difficult operating environment. A growing economy does not automatically mean consumers are feeling richer. Companies therefore have to distinguish between nominal market expansion and genuine increases in consumer purchasing power. That distinction will influence pricing, pack sizes, promotions, credit, product innovation and brand positioning.
The strategic implication is that Nigerian consumers may remain simultaneously more digitally connected and more financially cautious. That combination will reward brands capable of combining convenience and aspiration with demonstrable value.
BrandiQ Takeaway: Nigeria’s recovery is becoming more visible in the macroeconomic data, but the consumer recovery is more uneven. Businesses should therefore avoid reading GDP growth as a simple signal to raise prices or expand indiscriminately. The more useful question is where purchasing power, productivity and consumer confidence are actually returning.