Nigeria’s most trusted savings platform and a Lagos-based vehicle distributor have launched a car ownership scheme that begins at N5,000. The initiative is modest in its mechanics. Its implications are obvious for the brand and the prospective target market.
In Nigeria, a car is rarely just a car. It is a declaration of arrival, a proof of discipline, a statement that the distance between where you started and where you are going is being covered – slowly, perhaps, but measurably. For the millions of income-earning Nigerians for whom the outright purchase of a new vehicle has become an arithmetic impossibility in the wake of sustained naira depreciation and vehicle price inflation, that declaration has been deferred indefinitely. PiggyVest and Mikano Motors have decided to offer an alternative route.
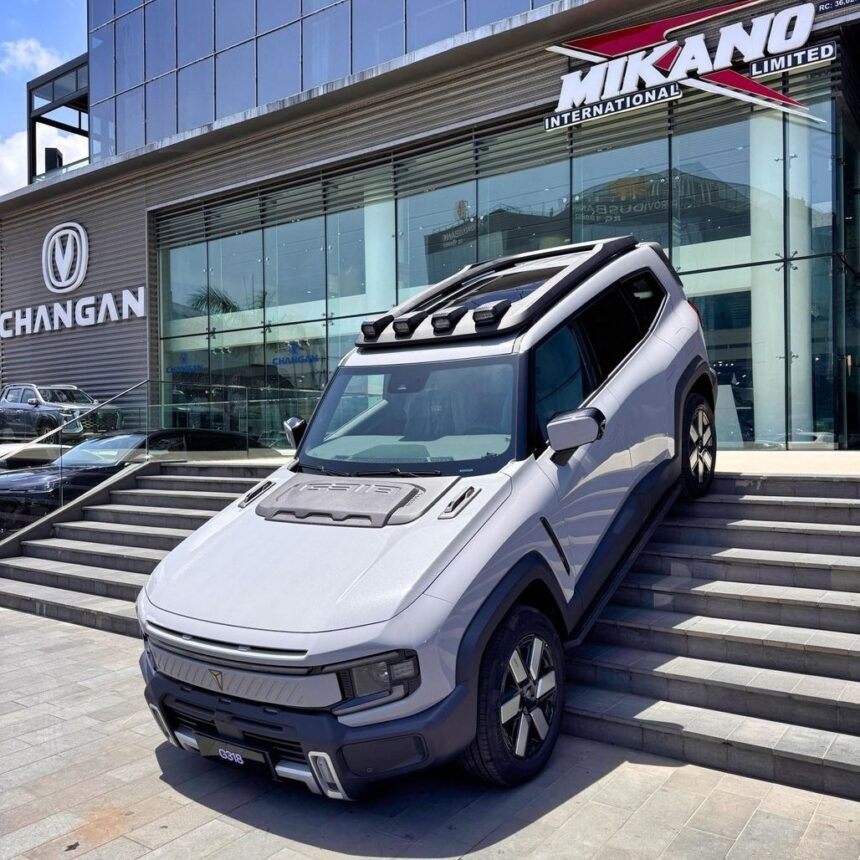
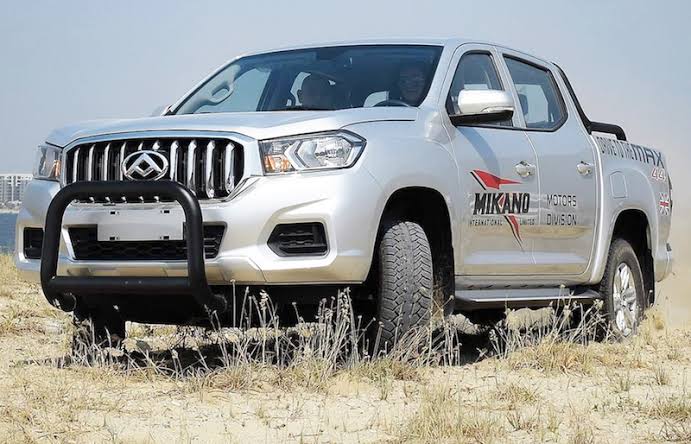
The partnership, unveiled at a press briefing in Lagos and branded “Own Your Dream Car with PiggyVest”, enables customers to select a Mikano vehicle directly on the PiggyVest platform – browsing available models, images and videos – and begin saving towards its purchase through PiggyVest’s “Get It” feature. The vehicle is delivered once the full payment target is reached. The scheme can be initiated with a saving of as little as N5,000 making the entry point accessible to a broad swathe of salaried and self-employed Nigerians who could not contemplate a lump-sum purchase but can commit to structured monthly discipline.
PiggyVest’s Chief Operating Officer, Ayo Akinola, framed the initiative straightforwardly at the launch: the partnership exists to address the affordability gap that rising vehicle prices have created. His Chief Marketing Officer, Joshua Chibueze, added that the scheme is open to all income-earning Nigerians who can maintain consistent savings behaviour, a qualification that is both a practical safeguard and an implicit statement about the platform’s core audience. PiggyVest has, since its founding in 2016 as Piggybank.ng, built its six million-strong user base around exactly this group: Nigerians who have income, who want to build something with it, and who need a structure that holds them to that intention.
Mikano Motors, for its part, brings automotive credibility to a category where consumer trust is a meaningful variable. Head of Operations Syam Abdulkadir cited the company’s “affordable luxury” positioning as the strategic alignment behind the partnership, and announced a N2 million cashback incentive for customers who complete their vehicle purchases within the scheme’s first twelve months – a commercial nudge designed to reward early completers and generate proof-of-concept testimonials within the programme’s critical first year.
There is, however, a detail buried in Abdulkadir’s remarks that deserves more attention than the launch coverage has given it. The scheme will operate under a dynamic pricing model – meaning that if vehicle prices increase during a customer’s savings period, the target amount can be revised upward. In an environment where the naira’s purchasing power has experienced sustained and at times dramatic erosion, this is not a theoretical risk. It is the condition under which most Nigerian consumer savings plans operate.
A customer who begins saving for a vehicle at today’s price and reaches their target twelve or eighteen months from now may find that the vehicle now costs more than they saved for. That is a consumer experience that could, if poorly managed, damage the trust both brands have spent years building.
How PiggyVest and Mikano manage that communication – with transparency, in advance, and with enough clarity that customers understand the risk before they begin rather than discover it at the point of completion, will determine whether this initiative fulfils its genuine commercial potential or becomes a cautionary tale about the distance between a product’s aspiration and its lived experience.
BRANDIQ ANALYSIS
The PiggyVest-Mikano partnership is, in its essentials, a brand strategy story as much as a financial products story. To understand why, it helps to understand what PiggyVest has built over the decade since its launch.
PiggyVest did not grow to six million users and N3 trillion in disbursements by offering higher interest rates than the banks. It grew by doing something considerably more valuable: it gave Nigerians a savings culture they could inhabit. The platform understood, from its earliest days, that the barrier to saving in Nigeria is not primarily access to a savings account. Almost everyone with a phone can open one.
The barrier is behavioural – the discipline problem, the temptation problem, the problem of wanting things now that you can only afford later. PiggyVest’s locked savings features, its withdrawal-day structure, its target savings tools, are all instruments of what behavioural economists call commitment mechanisms: they make it structurally harder to undo the decision to save than to keep saving. That design is PiggyVest’s real product, and it is what six million Nigerians have enrolled in.
The car ownership scheme extends this logic into one of the most emotionally resonant aspirational categories in the Nigerian consumer psyche. Car ownership in Lagos is not simply about transportation. It is about status, safety, time efficiency and social legibility. The market for new cars has been effectively narrowed, by exchange rate pressures and vehicle price inflation, to a segment of the population that most Nigerians do not occupy. PiggyVest is not solving that problem. But it is offering a structured pathway through it – one that starts at N5,000 which is within reach of a much larger proportion of Nigeria’s income-earning population than any dealership finance scheme currently serves.
The partnership is also a smart piece of brand architecture for Mikano Motors. Vehicle distributors in Nigeria face a dual commercial challenge: the addressable market for outright purchase has contracted, while the financing infrastructure that would expand it – bank auto loans at accessible rates – remains largely unavailable to middle-income buyers. By aligning with PiggyVest’s distribution, Mikano gains access to six million users who are already primed for goal-directed saving, already comfortable with a digital-first financial experience, and already disposed to trust the platform that is helping them build towards something. That is a warmer sales environment than any motor show or dealership advertisement can create.
The N2 million cashback incentive for early completers is commercially intelligent for a related reason. It creates a cohort of customers who finish the scheme within its first year, take delivery of their vehicle, and become the living evidence that the programme works. In a market where word-of-mouth and social proof carry enormous weight, a wave of verified “I saved with PiggyVest and drove away in a Mikano” testimonials is worth more than any launch campaign.
The dynamic pricing risk is the scheme’s most significant vulnerability, and both brands would be wise to address it with more public specificity than the launch communications offered. A scheme that begins with the promise of accessibility and ends with a customer discovering their target has moved is a scheme that produces exactly the kind of consumer frustration that damages not just the partnership but the trust infrastructure both brands depend on. PiggyVest’s greatest commercial asset is the belief, held by six million people, that it is a platform that does what it says. Dynamic pricing is a fair and commercially necessary provision in an inflationary environment. But it needs to be disclosed clearly, early and consistently – in the app interface, in the product terms and in the marketing communications – so that customers enter the scheme with accurate expectations rather than aspirational ones.
BrandiQ Verdict:
This is a strategically coherent partnership between two brands that have identified a genuine, large and underserved market need. The scheme’s entry point, its cultural resonance, its distribution logic and its incentive architecture are all well-considered. The dynamic pricing provision is the one element that requires more transparent consumer communication than the launch has so far provided. If PiggyVest manages that communication with the same clarity and trust it has applied to its core savings products, this initiative has the potential to become a template for how Nigerian fintech brands move beyond savings and investment into the broader landscape of aspirational consumer goods. A car today. A mortgage tomorrow. The ambition is legible. The execution, on this evidence, is promising.