WARC Media forecasts a rapidly maturing retail media market, but warns that the pursuit of advertising revenue could undermine shopper experience, creative effectiveness and the long-term value of the channel.
Retail media spend is the money brands invest in placing advertisements directly on a retailer’s digital or physical properties – such as sponsored product listings on e-commerce websites, app banners, or in-store digital screens. It uses first-party shopper data to target high-intent buyers right at the point of purchase
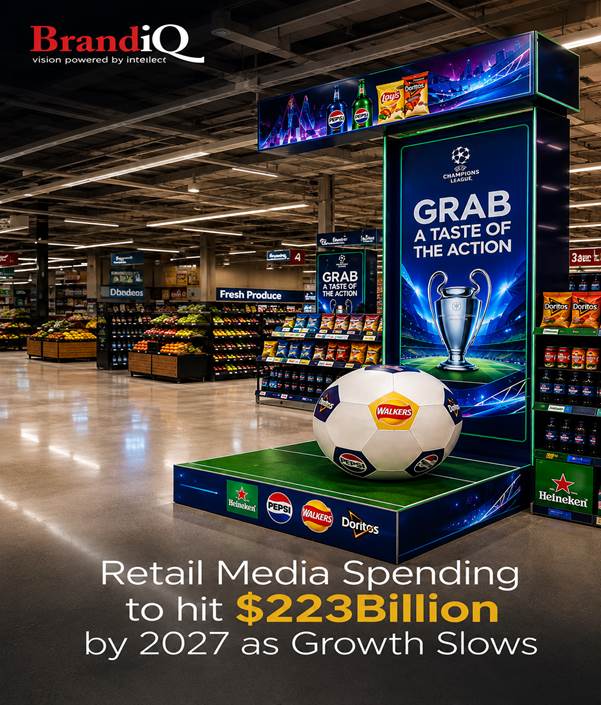
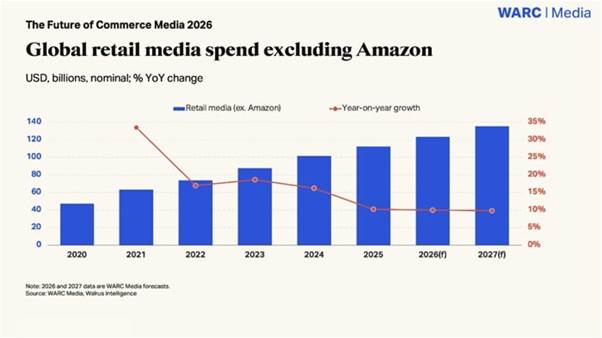
According to the latest forecast from WARC Media The Future of Commerce Media report, the global retail media market is continuing its rapid expansion, with worldwide advertising investment forecast to reach $200.4bn in 2026 and $223.4bn in 2027. The market is expected to grow by 11.5% year-on-year in 2027, when retail media will account for 15.2% of total worldwide advertising investment. Yet the figures also point to a market entering a more mature phase, with growth expected to move towards single digits. Excluding Amazon, global retail media growth is forecast to fall to 9.8% in 2027, the lowest year-on-year growth rate since WARC Media began tracking the market.
Alex Brownsell, head of content at WARC Media, said the changing market requires marketers and retailers to rethink how they approach commerce media. “The retail media landscape is maturing and consolidating, forcing marketers to rethink their approach,” he said. According to Brownsell, retail media remains particularly effective at converting existing demand but is less effective at long-term brand building, leaving retailers with a difficult balancing act between increasing advertising revenue and protecting the shopper experience.
The tension is becoming increasingly important as retail media networks (RMNs) pursue ambitious revenue targets. WARC Media warns that excessive advertising could produce what technology writer Cory Doctorow has called “enshittification” – a deterioration in the digital experience as platforms increasingly prioritise monetisation at the expense of users and business customers. Research cited by WARC found that Amazon, The Home Depot, Macy’s and Walmart each serve more than 20 advertisements per page on average, illustrating the pressure on retailers to increase advertising inventory.
Amazon continues to dominate
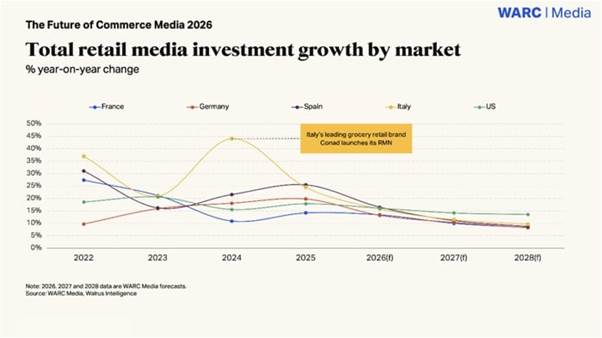
The United States remains a major force in retail media, with WARC Media forecasting US retail media network spending to grow 13.6% in 2028 to $74.9bn, even as European growth slows towards single digits. Concentration, however, remains a defining characteristic of the market. According to Walrus Intelligence, Amazon accounted for 78.0% of US retail media expenditure in 2025, while Walmart captured 7.5%, leaving only 14.5% for all other networks combined.
The concentration is similarly pronounced in Europe. More than two-thirds of overall retail media spending went to Amazon across France, Germany, Italy, Spain and the UK, according to the research. Amazon’s influence is also extending beyond conventional retail advertising: its non-retail advertising business, including Prime Video and Twitch, is projected to generate $6.7bn in 2027. As a standalone operation, that would make it the world’s second-largest commerce media business outside China, according to WARC Media.
This concentration raises an important strategic question for advertisers: whether retail media will develop into a genuinely competitive ecosystem of networks or become increasingly concentrated around a handful of platforms with enormous consumer data, transaction volumes and advertising infrastructure.
Retail Media Dominates Some Consumer Categories
Retail media has become particularly important to consumer-packaged goods advertisers. In 2027, WARC Media forecasts that retail media will account for 55.8% of all media investment by alcoholic drinks brands globally and 54.9% of total food-category media spending.
Its influence is considerably lower in technology and electronics, where retail media is expected to account for 15.0% of total spending in 2027, down from 16.2% in 2025. The difference suggests that the importance of retail media varies substantially according to purchase behaviour, product category and the relationship between advertising and the point of purchase.
The market also remains heavily dependent on a relatively small group of advertisers. Nearly 73.9% of UK brands spend with three or fewer retail media networks, while WARC Media’s analysis found that among eight of the UK’s largest domestic RMNs, none generates a third of its revenue from the long tail—the bottom 50% of brands by spending.
That concentration could become increasingly significant as retail media matures. A market dependent on a limited number of large advertisers may find it harder to sustain rapid growth once those advertisers reach practical limits on their budgets.
Retail media moves beyond the digital shelf
Retail media is also expanding into new formats and channels. Connected television already represents 23% of retail media spending, while WARC Media forecasts that video-on-demand will overtake retail media in global advertising investment by 2028.
Walmart’s acquisition of Vibe.co points towards another opportunity: bringing smaller, performance-focused brands into channels such as connected television. The development suggests that retail media networks could increasingly become broader commerce-media businesses rather than simply advertising environments attached to online stores.
For advertisers, this creates the possibility of connecting the purchase journey across multiple touchpoints. A consumer might encounter a brand through a creator, see it on connected television, encounter it on a retailer’s website and finally purchase it through the same retail ecosystem.
The experience problem
The industry’s biggest risk may therefore be less about whether retail media can grow and more about whether it can grow without damaging the environment in which consumers shop.
If retailers fill every available digital and physical surface with advertising, they may increase short-term advertising revenue while reducing the quality of the shopping experience. Irrelevant advertisements create friction, while excessive ad loads can make platforms feel less like useful retail environments and more like advertising marketplaces.
WARC Media consequently advises brands and retail media networks to create frictionless on-platform experiences, maximise relevance and minimise irrelevant advertising clutter. It also points to standardised measurement and the use of AI supported by robust datasets and deep consumer understanding as potential ways of improving effectiveness.
The warning is particularly relevant because retail media possesses an advantage that conventional advertising often lacks: proximity to purchase intent. But that advantage can be weakened if the advertising environment becomes so intrusive that consumers begin to distrust or avoid it.
Creative quality becomes more important
The research also challenges the assumption that being close to the transaction automatically makes retail media effective. According to an Ipsos study of simulated shopping experiences on Walmart and Amazon, memory encoding was 47% lower for advertisements appearing on retailer platforms than for advertisements appearing in generic offsite environments.
Creative quality therefore matters enormously. Among undecided shoppers, high creative quality produced a 12% lift in short-term brand choice, while among consumers not currently in the market, superior creative quality delivered a 21% performance advantage over low-quality advertising.
The findings suggest that retail media’s transactional advantage does not eliminate the fundamental principles of brand communication. Consumers still need to notice, remember and value a brand before advertising can create enduring commercial effects.
There is evidence of an opportunity in physical retail as well. More than half – 62% of US grocery buyers – say they have purchased a product directly after seeing it on an in-store screen. Yet WARC notes that in-store remains one of the least developed creative opportunities within retail media.
BrandiQ Analysis: The Retail Shelf is Becoming Media
The significance of the numbers goes beyond the size of the market. Retail media represents a fundamental convergence between commerce, data, technology and advertising. Retailers are no longer simply places where brands sell products; their platforms, customer data, websites, apps, stores and transaction environments are becoming media assets in their own right.
That creates enormous opportunities for marketers, but it also changes the strategic question. The objective cannot simply be to maximise impressions or advertisements. The stronger proposition is to connect media, context, consumer intent and experience.
This is where the warning about “enshittification” becomes particularly relevant. Retailers have access to something extremely valuable: consumers at or close to the point of purchase. If that privilege is exploited too aggressively, the very consumer trust and convenience that make retail media valuable could be damaged.
For brands, the implication is equally important. Retail media should not become an excuse to abandon brand building in favour of endless performance marketing. WARC Media’s own assessment is that the channel excels at converting existing demand but is weaker at creating long-term brand outcomes. The smarter strategy is therefore likely to connect retail media with broader brand-building activity rather than treating it as a substitute.
The most interesting possibilities may emerge where channels intersect – between physical retail and digital commerce, between creators and commerce platforms, and between brand storytelling and transaction data. In that model, retail media becomes not merely another advertising channel but part of a connected customer journey.
The $223.4bn forecast tells marketers that retail media is becoming too large to ignore. The slowing growth rate tells them something equally important: the next battle will not simply be for more advertising inventory. It will be for attention, relevance, memory and trust.